





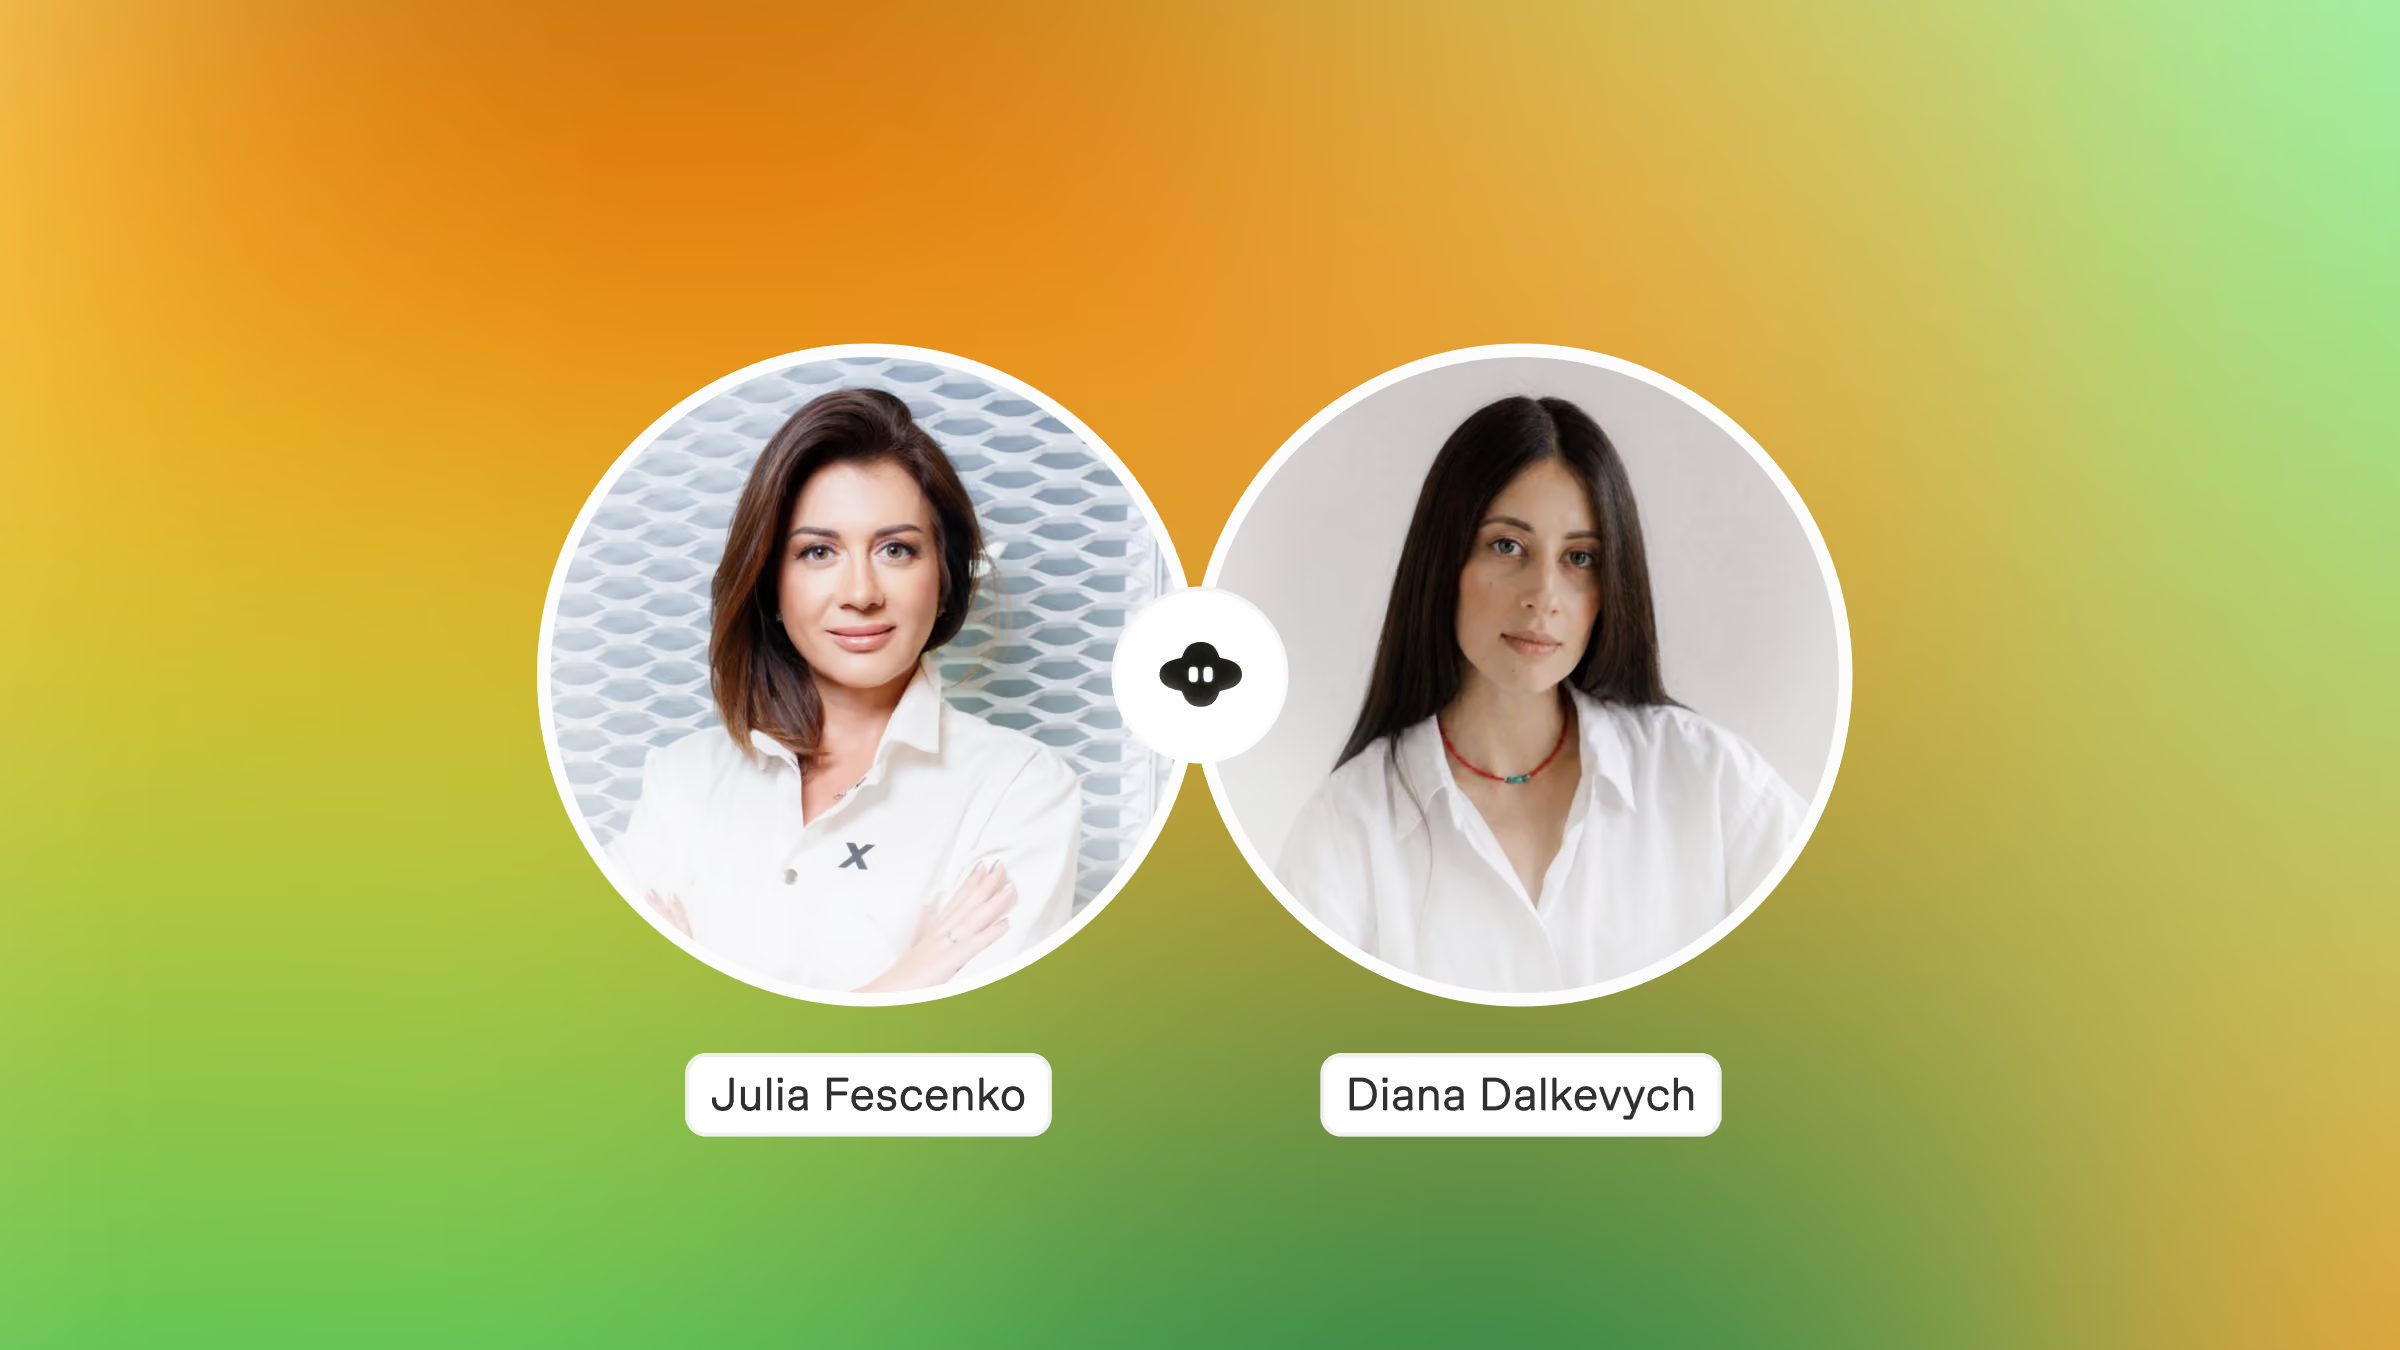
In this interview, we speak with Julia Fescenko, a FinTech and banking marketing expert at xpate and former Head of Marketing & Communications at Magnetiq Bank and PrivatBank Latvia. We discuss positioning, customer trust, product launches, opportunities in B2B payments, and collaboration with external teams.
This interview is conducted by our FinTech Growth Strategist, Diana Dalkevych.
From disruption to trust: how FinTech positioning has changed
Diana: What has changed most in how FinTech companies need to position and market themselves?
Julia: Earlier in my FinTech career, the marketing playbook felt fairly simple: build a sleek app or website, put "zero fees" on the homepage, and spend heavily on customer acquisition. The focus was on convenience, exciting features, and the promise of disrupting traditional banking.
That has changed quite dramatically. After a period of economic uncertainty and several high-profile failures in the industry, people became much more careful about whom they trust with their money.
FinTech has also become a powerful label in its own right. A term once used mainly by companies challenging traditional finance is now part of mainstream institutional branding. For marketers, that creates an interesting problem: when everyone wants to be FinTech, the word itself is no longer enough to differentiate you.
Diana: How should FinTech companies respond to that shift?
Julia: Today, trust matters as much as the product itself. A smooth interface and quick onboarding are still important, but customers also want to know where their money is held, how it is protected, and what happens if something goes wrong. Stability and financial discipline have become much stronger selling points than disruption.
Companies can no longer rely on paid advertising alone, either. Advertising on platforms such as Google and Meta has become more expensive, while customers are more sceptical of bold promises. Growth increasingly comes from building authority over time through useful content, transparent communication, and partnerships with brands people already know.
Credibility also has to be visible from the start. Security standards, regulatory status, and relevant certifications can no longer sit quietly in the footer. They need to be part of the main story. FinTech marketing used to be about showing how different you were from a bank. Now it is about showing that you can be trusted like one, while still offering a better experience.
Diana: When should a FinTech company reconsider its positioning?
Julia: A FinTech company should reconsider its positioning when the business has evolved, but the story it tells has stayed the same. You usually see this in sales conversations: prospects keep raising concerns that the messaging does not address, or deals repeatedly get stuck at the same stage.
Diana: Could you give an example?
Julia: Moving from SMBs to enterprise clients is a good example. You might start by selling a simple payout tool to small merchants, with messages such as "zero setup fees" and "five-minute onboarding". That can work very well for a small business.
The same pitch will fall flat with a large corporate client. Enterprise buyers are not impressed by a five-minute setup. They want to understand your API capabilities, security and compliance standards, role-based controls, and how customer funds are protected and segregated.
If your sales team keeps getting stuck in legal, compliance, or risk reviews, that is a strong signal. The product has grown up, but the way you talk about it has not. At that point, the company needs to reposition itself from a quick and convenient tool to a reliable piece of financial infrastructure.
Diana: How does brand development in FinTech differ from less regulated industries?
Julia: The biggest difference is that a FinTech brand cannot be developed by marketing in isolation. The promise you make has to match the product, the operational model, and what legal and compliance teams can support.
In many industries, a brand can win through novelty, convenience, or lifestyle appeal. In FinTech, you are asking people to trust you with their money, or asking a business to rely on you for a critical part of its operations. Naturally, every claim is examined more carefully.
That changes the process. Marketing has to work with product, legal, compliance, and risk from the beginning. You cannot make a bold claim about returns, speed, or security simply because it sounds good; you need to be able to prove it.
Diana: What does a buyer need to see before they decide to switch?
Julia: Customer reviews are helpful, but buyers also want to see security certifications, clear fund-protection models, regulatory status, and credible banking partners. The brand promise has to be visible in the way the business actually operates.
Switching costs are also much higher. Moving a payment system or primary financial account can be complicated and risky, so "slightly faster" is rarely a compelling reason to change. Positioning has to show that the value of switching clearly outweighs the effort and perceived risk.
Launching a product without positioning debt
Diana: Why do FinTech companies postpone brand and marketing work?
Julia: From what I’ve seen, this usually comes down to two things: the founders’ backgrounds and simple execution fatigue.
Building a FinTech company is incredibly demanding. Between obtaining licences, integrating with banking partners, developing the product, and setting up compliance, most of the team's early energy goes into engineering, legal, and operations. Brand and marketing are often treated as the "paint on the car" — something you add once the engine is running.
Diana: What happens when they wait until launch?
Julia: The problem is that companies can build up what I call "positioning debt". Without a clearly defined ideal customer, they end up creating twenty features for five different audiences. And when a product is built for five audiences, marketing often discovers that it is clearly for none of them.
The company launches, but no one immediately understands who the product is for or why it matters. The messaging becomes too broad, acquisition gets expensive because the company relies on cold advertising, and enterprise deals can stall because the brand does not communicate enough stability.
Fixing this after the product has been built is much harder and more expensive. You may need to rethink not only the website or campaign, but also the sales process, product roadmap, and sometimes even the product itself.
So, from my perspective, brand strategy should not be treated as a final layer. It should help shape what you build, who you build it for, and how you bring it to market from the very beginning.
Diana: What needs to be right before launching a banking or payments product?
Julia: Before thinking about campaigns, you need to know exactly who the product is for, what problem it solves, and why someone would choose it over the solution they already use.
That sounds obvious, but it is where many companies struggle. Banking and payments products often have a long list of features, so the messaging quickly becomes too broad. The real question is not whether the product offers faster payments or lower fees. It is what that means for the customer. Does it improve cash flow, reduce manual work, or make international expansion easier?
Diana: Once you know who you are selling to, what comes next?
Julia: The next question is distribution: how will the product actually reach customers? Paid advertising can support growth, but it is rarely enough on its own. Partnerships and integrations with accounting platforms or industry-specific software can be more effective because they place the product where customers already work and where some level of confidence already exists.
Finally, the customer experience has to support the promise. If the brand talks about simplicity but onboarding is long and confusing, credibility disappears very quickly. If you are selling to larger businesses, the experience needs to communicate reliability and expertise at every stage, from the website to sales and customer support.
Diana: Is the gap between the speed of product development and regulatory processes becoming a problem for FinTech?
Julia: Yes, it is a growing challenge, but I would not describe regulation itself as the problem. Financial products need strong controls because they deal with people's money. The challenge is that technology is moving much faster than the processes around it.
A small team using AI can now develop a convincing product very quickly. But making that product compliant, securing the right partners, and earning customer confidence still takes time. You can build a product quickly, but you cannot build credibility over a weekend.
For marketing, this creates a real risk. A company may start promoting the product before it is operationally ready, or make promises that compliance and product teams cannot fully support. That can damage credibility before the company has properly entered the market.
Diana: How can companies close that gap?
Julia: The solution starts with bringing product, compliance, legal, and marketing together much earlier. Marketing needs to understand the regulatory boundaries before developing the positioning, while compliance needs to understand how its requirements affect the customer experience.
Technology can make compliance processes faster and less manual, and established banking or infrastructure partners can shorten the route to market. But companies still need to explain clearly how the product works, why certain checks are required, and how customers' money and data are protected.
The goal should not be weaker regulation. It should be compliance that is more integrated, more technology-driven, and part of both the product and the brand from day one.
Where the opportunity is: B2B payments and business finance
Diana: Where do you see the strongest opportunity in FinTech today?
Julia: If I had to place a bet today, I would probably choose B2B cross-border payments, particularly the infrastructure that helps businesses manage payments across different markets.
Consumer payments are already very competitive, and margins can be difficult. But for many mid-sized businesses, moving money internationally is still slower, more expensive, and less transparent than it should be. They may work with several banks and payment providers, manage different currencies, and still have limited visibility over where their money is.
That is where I see a real opportunity. The value is not just a better FX rate. It is bringing payments, currency management, and treasury operations together, so businesses can manage international money movement with less complexity and more control.
I find this space especially interesting as a marketer because the customer problem is clear and the value is measurable. If you can help a company reduce costs, save time, and improve visibility into cash flow, you have a strong and relevant story to tell.
Reliability is essential because the product becomes part of the customer's daily operations. But if it is well integrated and consistently delivers value, it can create long-term relationships.
Diana: Which business finance problems are still not being solved well enough?
Julia: This connects with my earlier point about B2B payments. I would look at the financial challenges that smaller and mid-sized businesses face repeatedly but still manage through a combination of unrelated tools.
Many companies use one provider for banking, another for payments, separate accounting software, and several spreadsheets. The information exists, but it is fragmented, so getting a clear view of cash flow can still take a surprising amount of time.
Most existing products are good at showing what has already happened. The bigger opportunity is to help businesses understand what they should do next: when they may face a cash-flow gap, which invoices need attention, or how to manage payments across different accounts and currencies.
Diana: What would make a business pay for a solution like that?
Julia: If a product saves the finance team several hours each week, helps avoid a cash shortage, or improves control over working capital, the benefit is easy to understand and measure.
What makes this attractive from a marketing point of view is that the story is not based on another technical feature. It is based on a very human need: having a clear view of the company's finances and feeling more confident about the decisions you make.
Working with external teams
Diana: How does working with external teams differ between banks and FinTech companies?
Julia: The biggest difference, in my experience, is the pace of work — and the contrast is particularly clear when you compare a traditional bank with a FinTech company.
In a bank, the approval process can be very long. A new product may need to go through legal, compliance, risk, internal procedures, and sometimes the regulator. I experienced this with one banking product: marketing had prepared the positioning, campaign, and launch materials, but we were still waiting for the final documents and permissions. The whole process took more than a year. Marketing can be completely ready while the launch is waiting for one final approval — and then another final approval.
An external team working with a bank therefore needs patience and flexibility. Launch dates can move, materials may need to be updated several times, and a campaign can be ready long before the product is approved.
FinTech companies usually move much faster. They tend to have fewer layers of decision-making, shorter approval cycles, and a stronger culture of testing and iteration. Here, an external team has to respond quickly, work with incomplete information, and be comfortable adjusting the strategy as the product develops.
Diana: Which marketing capabilities make sense to keep in-house?
Julia: The capabilities you keep in-house should be the ones that depend most on a deep understanding of the business, the product, and the customer.
For me, that includes core brand strategy, product marketing, and customer insight. The internal team needs to understand what the company stands for, who it is trying to reach, and how the product creates value. It should own the final decisions around positioning and messaging. An external partner can challenge or help develop that thinking, but the company itself has to remain responsible for it.
Close collaboration with product, legal, and compliance also needs to happen internally. Marketing has to know what the product can genuinely promise and how to communicate it clearly without creating unnecessary risk. That context is difficult to transfer fully to an outside team.
Diana: When would you bring in external specialists?
Julia: External partners add the most value when you need specialist expertise, extra capacity, or a fresh perspective. That could include a rebranding project, crisis communications, PR in a new market, technical SEO, performance marketing, research, or a particular area of design. A good external team brings experience from other companies and can often see opportunities or problems that are less visible from inside the organisation.
I do not see this as a simple choice between internal and external teams. The strongest model is usually a combination: the internal team owns the strategy, context, and key decisions, while external specialists bring additional expertise and help execute at a higher level.
Diana: What do you look for when choosing an external team for a FinTech project?
Julia: The most important thing for me is whether the external team understands the market, not just design or marketing in general.
I saw this clearly when we were choosing an agency for a bank rebranding project. We needed a team that understood what FinTech means today, how customer expectations are changing, and how a financial brand can feel modern without losing credibility.
Knowledge of the competitive landscape was also important. We wanted the agency to know which banking and FinTech brands were setting the standard, what made them successful, and where the market was heading. Not because we wanted to copy those brands, but because you need to understand the category before you can create something distinctive within it.
Diana: What did you look for beyond their knowledge of the market?
Julia: We also looked closely at how each agency approached the problem. The strongest teams did not jump immediately into colours, logos, or visual concepts. They asked about customers, business strategy, positioning, and our ambitions for the brand. That showed us they were thinking beyond creative execution.
Finally, there has to be a good working relationship. Rebranding involves many discussions, different internal stakeholders, and sometimes difficult decisions. You need a team that listens, challenges you when necessary, and can clearly explain the thinking behind its recommendations.


